Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
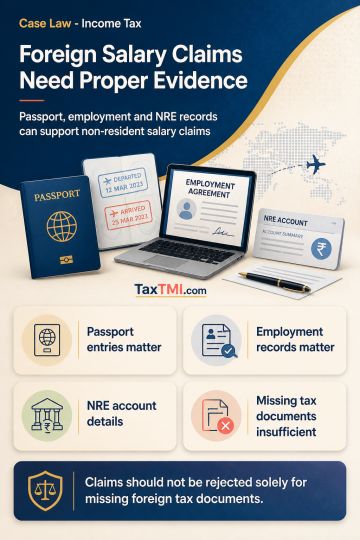
Foreign salary earned by a non-resident and received in USD in an NRE account requires assessment of evidence establishing foreign employment, non-residential status, and receipt of salary. Passport entries, employment records, and NRE account details are material evidence and should be considered. The absence of foreign tax returns, a tax residency certificate, or proof of foreign tax payment does not alone warrant rejection of the claim where available records support it. Assessment should address these documents without treating foreign tax records as a mandatory condition.
Foreign salary earned by a non-resident and received in USD in an NRE account requires assessment of evidence establishing foreign employment, non-residential status, and receipt of salary. Passport entries, employment records, and NRE account details are material evidence and should be considered. The absence of foreign tax returns, a tax residency certificate, or proof of foreign tax payment does not alone warrant rejection of the claim where available records support it. Assessment should address these documents without treating foreign tax records as a mandatory condition.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912