Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
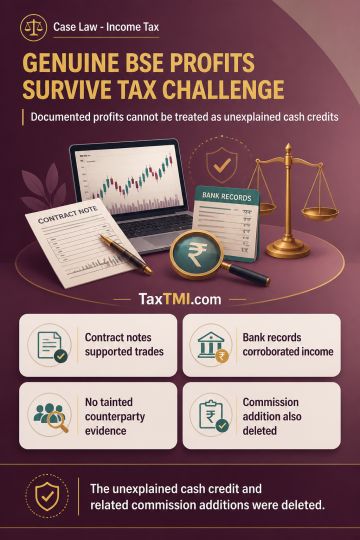
BSE futures and options trade profits disclosed for tax were supported by contract notes, tax records, bank statements, annual reports, transaction statements and account confirmations. Treating those profits as unexplained cash credit requires material showing that the broker or counterparty was tainted; no such material was identified. The preponderance-of-probabilities assessment distinguished alleged pre-arranged reversal trades involving loss-making entities from profitable trades with no identified loss-making counterparty. The trades were accepted as genuine, resulting in deletion of the unexplained cash credit addition and the consequential alleged commission expenditure addition under Section 69C.
BSE futures and options trade profits disclosed for tax were supported by contract notes, tax records, bank statements, annual reports, transaction statements and account confirmations. Treating those profits as unexplained cash credit requires material showing that the broker or counterparty was tainted; no such material was identified. The preponderance-of-probabilities assessment distinguished alleged pre-arranged reversal trades involving loss-making entities from profitable trades with no identified loss-making counterparty. The trades were accepted as genuine, resulting in deletion of the unexplained cash credit addition and the consequential alleged commission expenditure addition under Section 69C.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915