Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
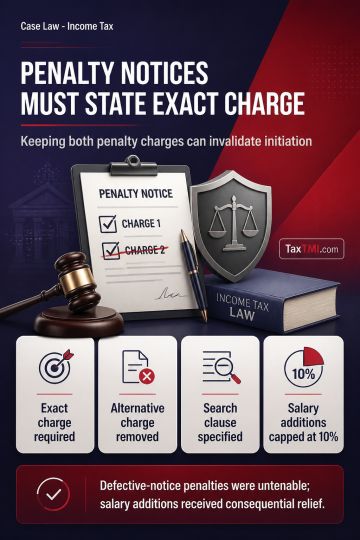
Penalty notices for concealment or furnishing inaccurate particulars must specify the exact charge and remove the inapplicable alternative; retaining both charges invalidates initiation. Similarly, search-penalty notices for undisclosed income must identify the applicable statutory clause because alternate clauses impose distinct conditions and consequences; non-specification makes the proceedings defective. Salary expenditure disallowed as allegedly non-genuine services was treated as requiring fact-based inquiry, but the related additions were restricted to 10% with consequential relief. Penalties based on defective notices were untenable.
Penalty notices for concealment or furnishing inaccurate particulars must specify the exact charge and remove the inapplicable alternative; retaining both charges invalidates initiation. Similarly, search-penalty notices for undisclosed income must identify the applicable statutory clause because alternate clauses impose distinct conditions and consequences; non-specification makes the proceedings defective. Salary expenditure disallowed as allegedly non-genuine services was treated as requiring fact-based inquiry, but the related additions were restricted to 10% with consequential relief. Penalties based on defective notices were untenable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905