Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
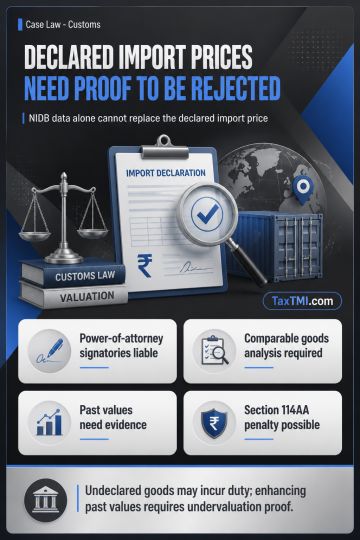
Beneficial owners exercising effective control over imported goods may be treated as importers and held liable for customs duty, interest, penalty and fine, including authorised signatories acting under powers of attorney for a deceased sole proprietor. Transaction value cannot be rejected merely on NIDB data unless evidence establishes that the declared price was not the price actually paid or payable, supported by comparable-goods analysis. Where quantity misdeclaration is admitted, duty may be recovered on undeclared goods at the declared value. Findings on live consignments cannot, without proof of undervaluation, justify enhancing assessable value of past cleared consignments or confiscating them. A substantial non-bona-fide quantity discrepancy may sustain penalty under Section 114AA, although other penalty and confiscation directions may fail.
Beneficial owners exercising effective control over imported goods may be treated as importers and held liable for customs duty, interest, penalty and fine, including authorised signatories acting under powers of attorney for a deceased sole proprietor. Transaction value cannot be rejected merely on NIDB data unless evidence establishes that the declared price was not the price actually paid or payable, supported by comparable-goods analysis. Where quantity misdeclaration is admitted, duty may be recovered on undeclared goods at the declared value. Findings on live consignments cannot, without proof of undervaluation, justify enhancing assessable value of past cleared consignments or confiscating them. A substantial non-bona-fide quantity discrepancy may sustain penalty under Section 114AA, although other penalty and confiscation directions may fail.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912