Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
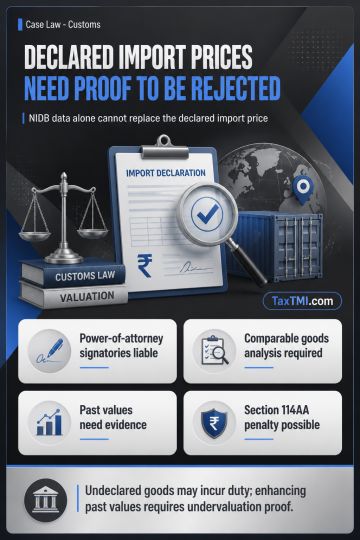
Beneficial owners exercising effective control over imported goods may be treated as importers and held liable for customs duty, interest, penalty and fine, including authorised signatories acting under powers of attorney for a deceased sole proprietor. Transaction value cannot be rejected merely on NIDB data unless evidence establishes that the declared price was not the price actually paid or payable, supported by comparable-goods analysis. Where quantity misdeclaration is admitted, duty may be recovered on undeclared goods at the declared value. Findings on live consignments cannot, without proof of undervaluation, justify enhancing assessable value of past cleared consignments or confiscating them. A substantial non-bona-fide quantity discrepancy may sustain penalty under Section 114AA, although other penalty and confiscation directions may fail.
Beneficial owners exercising effective control over imported goods may be treated as importers and held liable for customs duty, interest, penalty and fine, including authorised signatories acting under powers of attorney for a deceased sole proprietor. Transaction value cannot be rejected merely on NIDB data unless evidence establishes that the declared price was not the price actually paid or payable, supported by comparable-goods analysis. Where quantity misdeclaration is admitted, duty may be recovered on undeclared goods at the declared value. Findings on live consignments cannot, without proof of undervaluation, justify enhancing assessable value of past cleared consignments or confiscating them. A substantial non-bona-fide quantity discrepancy may sustain penalty under Section 114AA, although other penalty and confiscation directions may fail.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915