Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
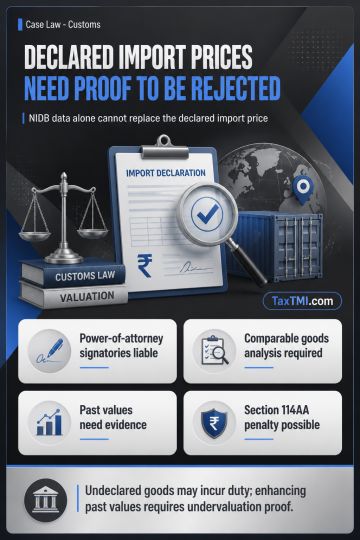
Beneficial owners exercising effective control over imported goods may be treated as importers and held liable for customs duty, interest, penalty and fine, including authorised signatories acting under powers of attorney for a deceased sole proprietor. Transaction value cannot be rejected merely on NIDB data unless evidence establishes that the declared price was not the price actually paid or payable, supported by comparable-goods analysis. Where quantity misdeclaration is admitted, duty may be recovered on undeclared goods at the declared value. Findings on live consignments cannot, without proof of undervaluation, justify enhancing assessable value of past cleared consignments or confiscating them. A substantial non-bona-fide quantity discrepancy may sustain penalty under Section 114AA, although other penalty and confiscation directions may fail.
Beneficial owners exercising effective control over imported goods may be treated as importers and held liable for customs duty, interest, penalty and fine, including authorised signatories acting under powers of attorney for a deceased sole proprietor. Transaction value cannot be rejected merely on NIDB data unless evidence establishes that the declared price was not the price actually paid or payable, supported by comparable-goods analysis. Where quantity misdeclaration is admitted, duty may be recovered on undeclared goods at the declared value. Findings on live consignments cannot, without proof of undervaluation, justify enhancing assessable value of past cleared consignments or confiscating them. A substantial non-bona-fide quantity discrepancy may sustain penalty under Section 114AA, although other penalty and confiscation directions may fail.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4907