Document Identification Number compliance renders TDS-default orders invalid where mandatory DIN requirements are breached and curative provision does...
Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Page of 4921
Press 'Enter' after typing page number.
221 to 240 of 98411 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
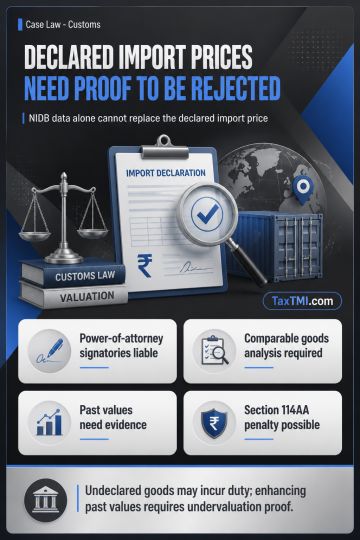
Beneficial owners exercising effective control over imported goods may be treated as importers and held liable for customs duty, interest, penalty and fine, including authorised signatories acting under powers of attorney for a deceased sole proprietor. Transaction value cannot be rejected merely on NIDB data unless evidence establishes that the declared price was not the price actually paid or payable, supported by comparable-goods analysis. Where quantity misdeclaration is admitted, duty may be recovered on undeclared goods at the declared value. Findings on live consignments cannot, without proof of undervaluation, justify enhancing assessable value of past cleared consignments or confiscating them. A substantial non-bona-fide quantity discrepancy may sustain penalty under Section 114AA, although other penalty and confiscation directions may fail.
Beneficial owners exercising effective control over imported goods may be treated as importers and held liable for customs duty, interest, penalty and fine, including authorised signatories acting under powers of attorney for a deceased sole proprietor. Transaction value cannot be rejected merely on NIDB data unless evidence establishes that the declared price was not the price actually paid or payable, supported by comparable-goods analysis. Where quantity misdeclaration is admitted, duty may be recovered on undeclared goods at the declared value. Findings on live consignments cannot, without proof of undervaluation, justify enhancing assessable value of past cleared consignments or confiscating them. A substantial non-bona-fide quantity discrepancy may sustain penalty under Section 114AA, although other penalty and confiscation directions may fail.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921