Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
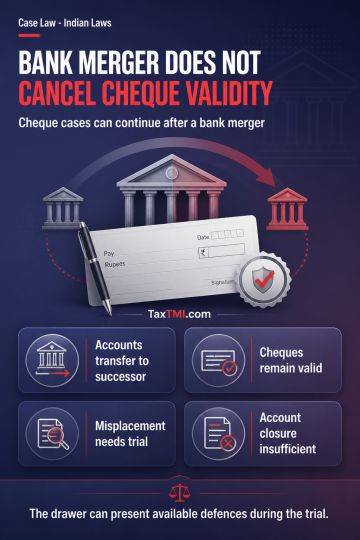
Merger of a drawee bank transfers its assets, liabilities and customer accounts to the resulting bank; it does not extinguish the account or invalidate a cheque drawn on it. The cheque recipient may present the cheque without fault despite the merger. Claims that the cheque was misplaced constitute a defence requiring trial, rather than a ground to quash cheque-dishonour proceedings. Account closure likewise does not justify quashing. Cheque-dishonour proceedings therefore continue, with the drawer retaining liberty to raise available defences during trial.
Merger of a drawee bank transfers its assets, liabilities and customer accounts to the resulting bank; it does not extinguish the account or invalidate a cheque drawn on it. The cheque recipient may present the cheque without fault despite the merger. Claims that the cheque was misplaced constitute a defence requiring trial, rather than a ground to quash cheque-dishonour proceedings. Account closure likewise does not justify quashing. Cheque-dishonour proceedings therefore continue, with the drawer retaining liberty to raise available defences during trial.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912