Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
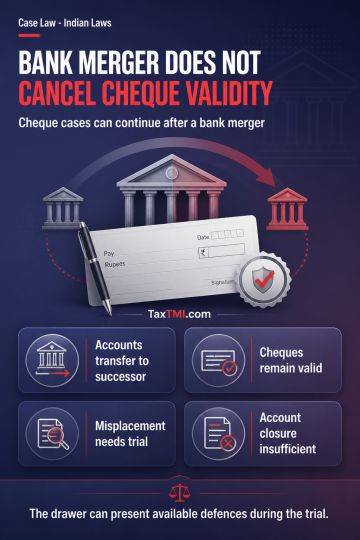
Merger of a drawee bank transfers its assets, liabilities and customer accounts to the resulting bank; it does not extinguish the account or invalidate a cheque drawn on it. The cheque recipient may present the cheque without fault despite the merger. Claims that the cheque was misplaced constitute a defence requiring trial, rather than a ground to quash cheque-dishonour proceedings. Account closure likewise does not justify quashing. Cheque-dishonour proceedings therefore continue, with the drawer retaining liberty to raise available defences during trial.
Merger of a drawee bank transfers its assets, liabilities and customer accounts to the resulting bank; it does not extinguish the account or invalidate a cheque drawn on it. The cheque recipient may present the cheque without fault despite the merger. Claims that the cheque was misplaced constitute a defence requiring trial, rather than a ground to quash cheque-dishonour proceedings. Account closure likewise does not justify quashing. Cheque-dishonour proceedings therefore continue, with the drawer retaining liberty to raise available defences during trial.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910