Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
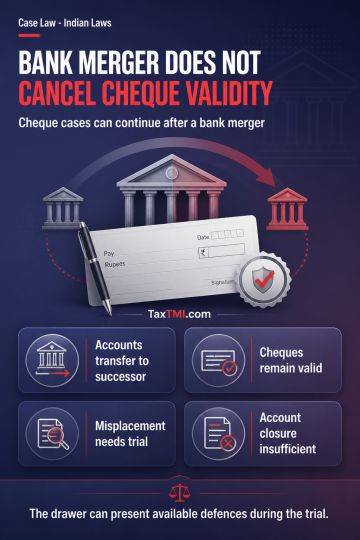
Merger of a drawee bank transfers its assets, liabilities and customer accounts to the resulting bank; it does not extinguish the account or invalidate a cheque drawn on it. The cheque recipient may present the cheque without fault despite the merger. Claims that the cheque was misplaced constitute a defence requiring trial, rather than a ground to quash cheque-dishonour proceedings. Account closure likewise does not justify quashing. Cheque-dishonour proceedings therefore continue, with the drawer retaining liberty to raise available defences during trial.
Merger of a drawee bank transfers its assets, liabilities and customer accounts to the resulting bank; it does not extinguish the account or invalidate a cheque drawn on it. The cheque recipient may present the cheque without fault despite the merger. Claims that the cheque was misplaced constitute a defence requiring trial, rather than a ground to quash cheque-dishonour proceedings. Account closure likewise does not justify quashing. Cheque-dishonour proceedings therefore continue, with the drawer retaining liberty to raise available defences during trial.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913