Mobile-phone electronic evidence failed to establish customs undervaluation, while duty survived on non-authentic origin certificates without importer...
Automotive radio classification treats integrated infotainment features as supplementary, placing complete and qualifying unassembled units under the ...
Separate corporate personality prevents directors from being personally liable for company deposits without a guarantee or independent legal undertaki...
Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
Power bank definition limits the customs-duty exclusion, preserving concessional treatment for stationary, grid-scale and industrial battery storage s...
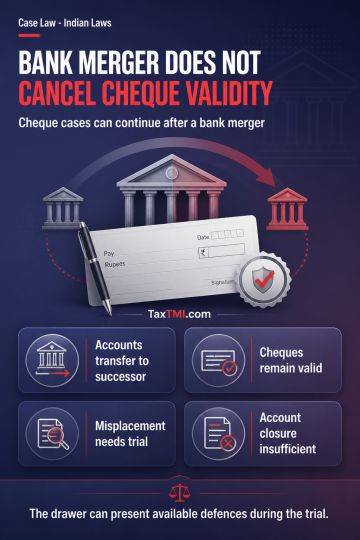
Merger of a drawee bank transfers its assets, liabilities and customer accounts to the resulting bank; it does not extinguish the account or invalidate a cheque drawn on it. The cheque recipient may present the cheque without fault despite the merger. Claims that the cheque was misplaced constitute a defence requiring trial, rather than a ground to quash cheque-dishonour proceedings. Account closure likewise does not justify quashing. Cheque-dishonour proceedings therefore continue, with the drawer retaining liberty to raise available defences during trial.
Merger of a drawee bank transfers its assets, liabilities and customer accounts to the resulting bank; it does not extinguish the account or invalidate a cheque drawn on it. The cheque recipient may present the cheque without fault despite the merger. Claims that the cheque was misplaced constitute a defence requiring trial, rather than a ground to quash cheque-dishonour proceedings. Account closure likewise does not justify quashing. Cheque-dishonour proceedings therefore continue, with the drawer retaining liberty to raise available defences during trial.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913