Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
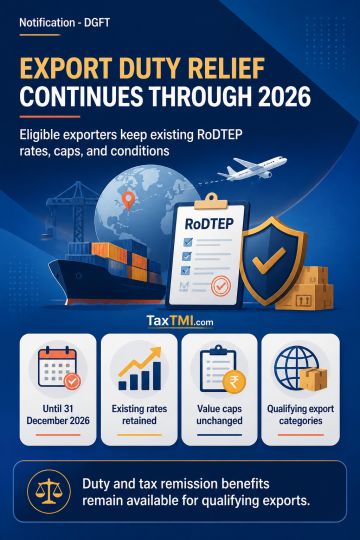
The RoDTEP Scheme continues until 31 December 2026 for eligible exports made by Domestic Tariff Area units, Advance Authorisation holders, Special Economic Zone units and Export Oriented Units. Existing RoDTEP rates and value caps applicable on 30 September 2026 remain unchanged throughout the extended period. All other scheme terms and conditions also continue without modification, preserving duty and tax remission benefits for qualifying exports within the stated categories.
The RoDTEP Scheme continues until 31 December 2026 for eligible exports made by Domestic Tariff Area units, Advance Authorisation holders, Special Economic Zone units and Export Oriented Units. Existing RoDTEP rates and value caps applicable on 30 September 2026 remain unchanged throughout the extended period. All other scheme terms and conditions also continue without modification, preserving duty and tax remission benefits for qualifying exports within the stated categories.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910