Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
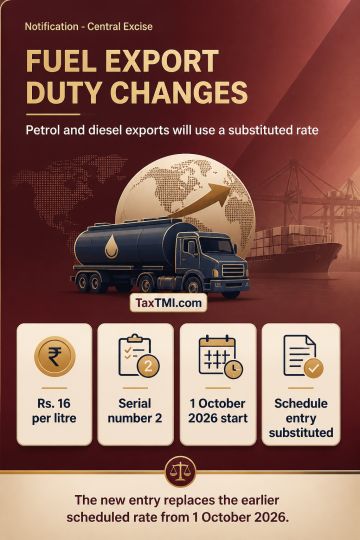
The special additional excise duty schedule governing petrol and diesel exports is amended: the entry in column (4) against serial number 2 is substituted with a rate of Rs. 16 per litre. Effective 1 October 2026, the substituted rate replaces the prior rate specified for that serial number under the existing duty schedule.
The special additional excise duty schedule governing petrol and diesel exports is amended: the entry in column (4) against serial number 2 is substituted with a rate of Rs. 16 per litre. Effective 1 October 2026, the substituted rate replaces the prior rate specified for that serial number under the existing duty schedule.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915