Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
Factory-consumption condition restricts solar module parts exemption and excludes imported aluminium profiles fabricated outside the production factor...
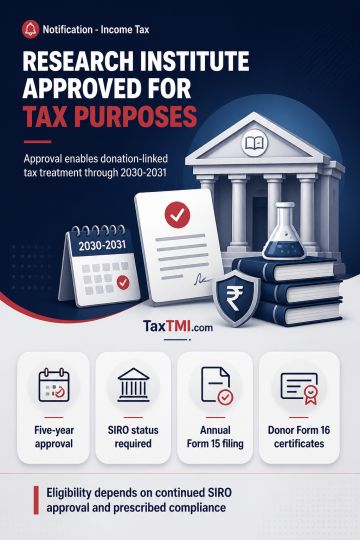
Institute for Financial Management and Research is approved as an institution for social science or statistical research under the university, college or other institution category for the specified Income-tax Act purposes. The approval applies for tax years 2026-2027 through 2030-2031, subject to continued Scientific and Industrial Research Organisation approval in every relevant tax year. The institution must comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the tax year of receipt, and issue donors a Form No. 16 certificate stating the donation amount.
Institute for Financial Management and Research is approved as an institution for social science or statistical research under the university, college or other institution category for the specified Income-tax Act purposes. The approval applies for tax years 2026-2027 through 2030-2031, subject to continued Scientific and Industrial Research Organisation approval in every relevant tax year. The institution must comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the tax year of receipt, and issue donors a Form No. 16 certificate stating the donation amount.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913