Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
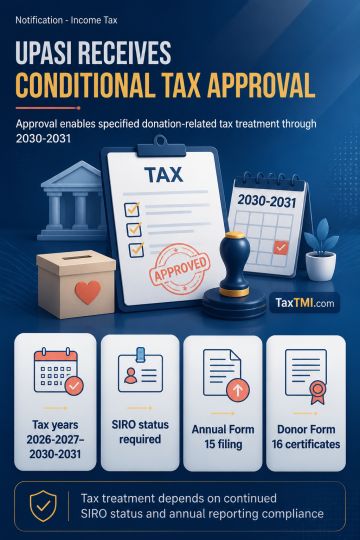
UPASI Tea Research Foundation is approved as an 'Other Institution' for scientific research purposes under the Income-tax Act, enabling the specified donation-related tax treatment. The approval applies for tax years 2026-2027 to 2030-2031 and remains conditional on the foundation retaining Scientific and Industrial Research Organization approval throughout each relevant tax year. It must also comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the relevant tax year, and provide donors with Form No. 16 certificates stating the donation amount.
UPASI Tea Research Foundation is approved as an 'Other Institution' for scientific research purposes under the Income-tax Act, enabling the specified donation-related tax treatment. The approval applies for tax years 2026-2027 to 2030-2031 and remains conditional on the foundation retaining Scientific and Industrial Research Organization approval throughout each relevant tax year. It must also comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the relevant tax year, and provide donors with Form No. 16 certificates stating the donation amount.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913