Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
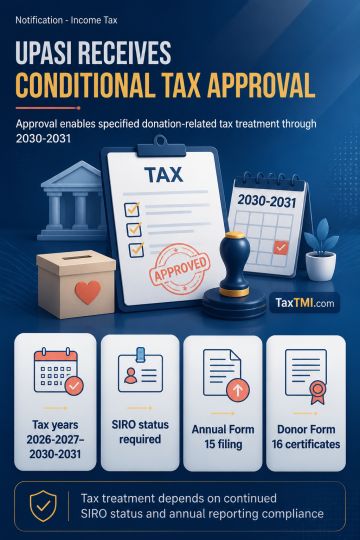
UPASI Tea Research Foundation is approved as an 'Other Institution' for scientific research purposes under the Income-tax Act, enabling the specified donation-related tax treatment. The approval applies for tax years 2026-2027 to 2030-2031 and remains conditional on the foundation retaining Scientific and Industrial Research Organization approval throughout each relevant tax year. It must also comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the relevant tax year, and provide donors with Form No. 16 certificates stating the donation amount.
UPASI Tea Research Foundation is approved as an 'Other Institution' for scientific research purposes under the Income-tax Act, enabling the specified donation-related tax treatment. The approval applies for tax years 2026-2027 to 2030-2031 and remains conditional on the foundation retaining Scientific and Industrial Research Organization approval throughout each relevant tax year. It must also comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the relevant tax year, and provide donors with Form No. 16 certificates stating the donation amount.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915