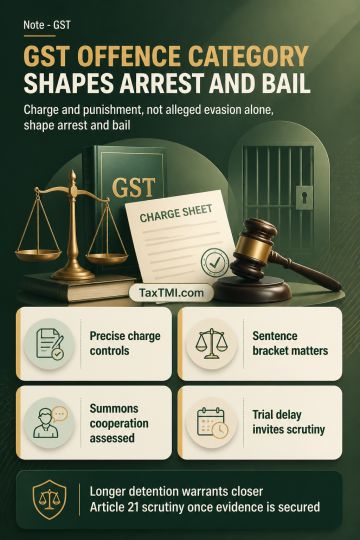
GST offence classification determines whether arrest and bail restrictions apply, while continued custody requires an individualised necessity assessm...
Page of 4918
Press 'Enter' after typing page number.
261 to 280 of 98352 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
GSTR-1 and GSTR-3B mismatch requires verification of its cause, reconciliation with liability records and subsequent payments, and a determination whether tax remains unpaid; a numerical difference alone cannot establish short payment. Input tax credit reversal demands require a separate statutory basis and computation. Ex parte disposal following non-appearance remains subject to a reasoned determination of material grounds. Statutory claims concerning interest and penalty waiver, service of notices, and duplicate proceedings require examination against applicable conditions and records. The appellate order was set aside and remanded for fresh determination of actual liability and statutory claims.
GSTR-1 and GSTR-3B mismatch requires verification of its cause, reconciliation with liability records and subsequent payments, and a determination whether tax remains unpaid; a numerical difference alone cannot establish short payment. Input tax credit reversal demands require a separate statutory basis and computation. Ex parte disposal following non-appearance remains subject to a reasoned determination of material grounds. Statutory claims concerning interest and penalty waiver, service of notices, and duplicate proceedings require examination against applicable conditions and records. The appellate order was set aside and remanded for fresh determination of actual liability and statutory claims.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918