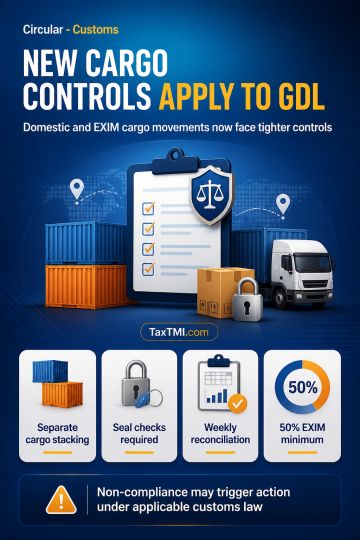
Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
Page of 4910
Press 'Enter' after typing page number.
641 to 660 of 98195 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Regional Rural Banks are deemed to be co-operative societies for Income-tax Act purposes under the statutory fiction in section 22 of the Regional Rural Banks Act. That fiction remains effective because section 80P(4) does not displace it, and definitions of primary co-operative bank or primary credit society are inapplicable where the bank is not claimed to fall within those categories. Deduction under section 80P is therefore available. An assessment correctly granting that deduction is not erroneous and prejudicial to the interests of the Revenue, limiting revision under section 263.
Regional Rural Banks are deemed to be co-operative societies for Income-tax Act purposes under the statutory fiction in section 22 of the Regional Rural Banks Act. That fiction remains effective because section 80P(4) does not displace it, and definitions of primary co-operative bank or primary credit society are inapplicable where the bank is not claimed to fall within those categories. Deduction under section 80P is therefore available. An assessment correctly granting that deduction is not erroneous and prejudicial to the interests of the Revenue, limiting revision under section 263.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910