Document Identification Number compliance renders TDS-default orders invalid where mandatory DIN requirements are breached and curative provision does...
Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
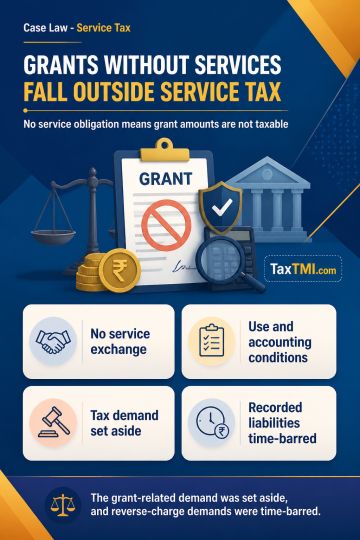
Government grants-in-aid do not constitute consideration for Business Exhibition Service where agreements impose only utilisation and accounting conditions, without an obligation to provide services, invoices, or quid pro quo. As reimbursement of specified expenditure, they fall outside taxable value, which is confined to amounts charged for taxable services; the related demand was set aside. Extended limitation cannot apply where grants and expenditure were recorded, the taxpayer paid tax on other services, and a bona fide belief of non-taxability negated suppression with intent to evade. Reverse-charge demands were likewise time-barred because recorded liabilities were revenue neutral through available Cenvat credit.
Government grants-in-aid do not constitute consideration for Business Exhibition Service where agreements impose only utilisation and accounting conditions, without an obligation to provide services, invoices, or quid pro quo. As reimbursement of specified expenditure, they fall outside taxable value, which is confined to amounts charged for taxable services; the related demand was set aside. Extended limitation cannot apply where grants and expenditure were recorded, the taxpayer paid tax on other services, and a bona fide belief of non-taxability negated suppression with intent to evade. Reverse-charge demands were likewise time-barred because recorded liabilities were revenue neutral through available Cenvat credit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI