Independent manufacturing undertaking eligibility preserves Section 80IA/80IB deductions, while machinery kept ready for use qualifies for depreciatio...
Assessing Officer Satisfaction Requirement Bars Penalty for Cash Receipt in Immovable-Property Sale Cases Where Initiation Lacks Recorded Satisfaction...
Self-assessed import entries remain appealable, while bona fide classification disputes without misdeclaration cannot justify confiscation or penaltie...
Actual-user customs exemption conditions permit turnkey project transfers when imported windmill components are exclusively used for installation and ...
Customs offence disqualification excludes civil contraventions, preventing refusal of a private bonded warehouse licence based solely on monetary pena...
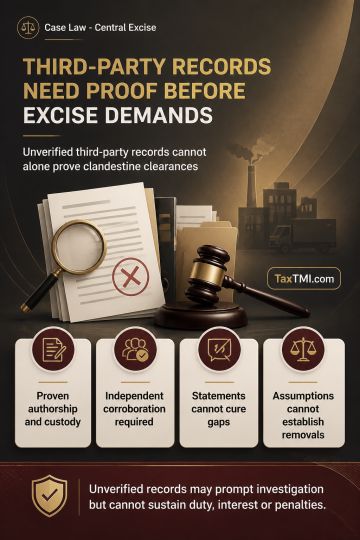
Clandestine manufacture and clearance allegations require sufficient tangible evidence establishing a reliable chain from unaccounted inputs and production to transport, buyers and receipt of sale proceeds. Loose handwritten sheets, WhatsApp printouts, Tally data and transporter records maintained or recovered from third parties cannot substantiate a demand unless their authorship, provenance, custody, preservation, integrity and nexus with the manufacturer are proved. Unretracted statements showing a marketing or distribution connection do not remedy defects in electronic evidence. Inferences drawn through assumed material consumption, manufacture and removal are impermissible successive presumptions. Unverified records may justify further investigation but cannot, without independent corroboration, sustain duty, interest or penalties.
Clandestine manufacture and clearance allegations require sufficient tangible evidence establishing a reliable chain from unaccounted inputs and production to transport, buyers and receipt of sale proceeds. Loose handwritten sheets, WhatsApp printouts, Tally data and transporter records maintained or recovered from third parties cannot substantiate a demand unless their authorship, provenance, custody, preservation, integrity and nexus with the manufacturer are proved. Unretracted statements showing a marketing or distribution connection do not remedy defects in electronic evidence. Inferences drawn through assumed material consumption, manufacture and removal are impermissible successive presumptions. Unverified records may justify further investigation but cannot, without independent corroboration, sustain duty, interest or penalties.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918