TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
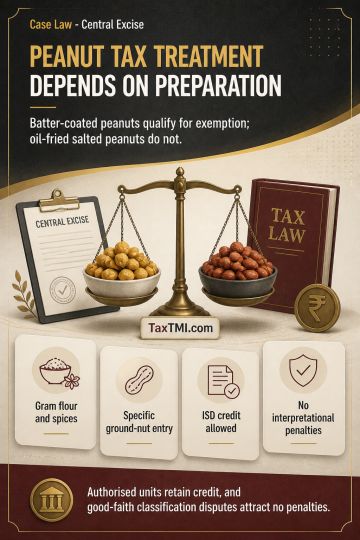
Batter-coated, deep-fried Tasty Peanuts containing gram flour, salt and spices constitute a distinct food preparation classified under the food-preparation tariff entry, attracting the stated exemption. Oil-fried Salted Peanuts with salt alone remain within the specific ground-nut entry because it expressly covers nuts roasted in oil or fat with salt, flavours or spices; their exemption is unavailable. ISD-distributed CENVAT credit is available to an authorised contract manufacturing unit producing dutiable goods for the principal, with subsequent amendments curing the earlier lacuna from inception. Penalties do not arise from bona fide tariff-classification and CENVAT-credit interpretation disputes without fraud, suppression, collusion, wilful intent to evade duty or mens rea.
Batter-coated, deep-fried Tasty Peanuts containing gram flour, salt and spices constitute a distinct food preparation classified under the food-preparation tariff entry, attracting the stated exemption. Oil-fried Salted Peanuts with salt alone remain within the specific ground-nut entry because it expressly covers nuts roasted in oil or fat with salt, flavours or spices; their exemption is unavailable. ISD-distributed CENVAT credit is available to an authorised contract manufacturing unit producing dutiable goods for the principal, with subsequent amendments curing the earlier lacuna from inception. Penalties do not arise from bona fide tariff-classification and CENVAT-credit interpretation disputes without fraud, suppression, collusion, wilful intent to evade duty or mens rea.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912