Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensa...
Resolution plan finality extinguishes unquantified operational-creditor claims and pending proceedings unless the approved plan expressly preserves th...
Stakeholder-list modification permits liquidators to update entries on new information, subject to notifying the Adjudicating Authority within prescri...
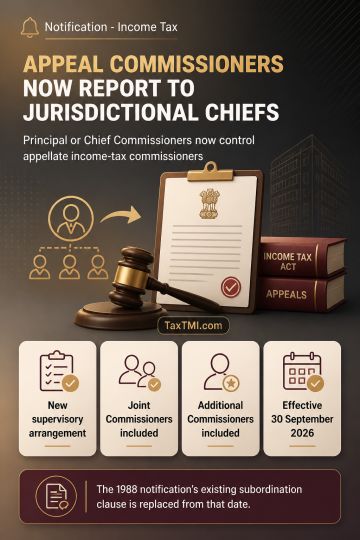
Joint Commissioners of Income-tax (Appeals) and Additional Commissioners of Income-tax (Appeals) are placed under the control of the Principal Chief Commissioners of Income-tax or Chief Commissioners of Income-tax within whose jurisdiction they perform their functions. This substitutes the existing clause governing their subordination under the 1988 notification and takes effect from 30 September 2026, the date of publication in the Official Gazette.
Joint Commissioners of Income-tax (Appeals) and Additional Commissioners of Income-tax (Appeals) are placed under the control of the Principal Chief Commissioners of Income-tax or Chief Commissioners of Income-tax within whose jurisdiction they perform their functions. This substitutes the existing clause governing their subordination under the 1988 notification and takes effect from 30 September 2026, the date of publication in the Official Gazette.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913