SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Page of 4910
Press 'Enter' after typing page number.
761 to 780 of 98196 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
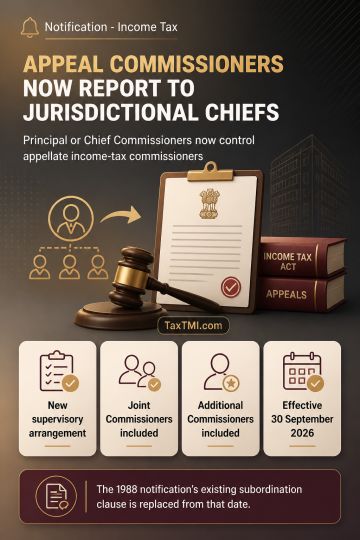
Joint Commissioners of Income-tax (Appeals) and Additional Commissioners of Income-tax (Appeals) are placed under the control of the Principal Chief Commissioners of Income-tax or Chief Commissioners of Income-tax within whose jurisdiction they perform their functions. This substitutes the existing clause governing their subordination under the 1988 notification and takes effect from 30 September 2026, the date of publication in the Official Gazette.
Joint Commissioners of Income-tax (Appeals) and Additional Commissioners of Income-tax (Appeals) are placed under the control of the Principal Chief Commissioners of Income-tax or Chief Commissioners of Income-tax within whose jurisdiction they perform their functions. This substitutes the existing clause governing their subordination under the 1988 notification and takes effect from 30 September 2026, the date of publication in the Official Gazette.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910