Transfer-pricing aggregation of distinct support-service and subcontract transactions was rejected, while debt-free receivables attracted no notional ...
Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
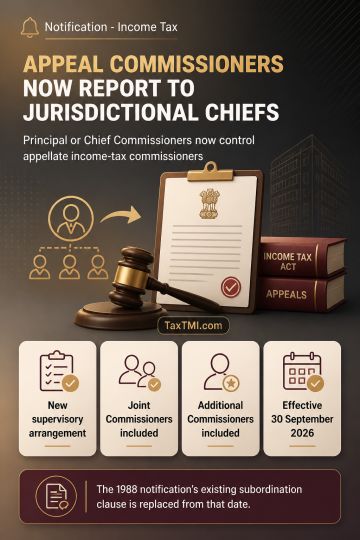
Joint Commissioners of Income-tax (Appeals) and Additional Commissioners of Income-tax (Appeals) are placed under the control of the Principal Chief Commissioners of Income-tax or Chief Commissioners of Income-tax within whose jurisdiction they perform their functions. This substitutes the existing clause governing their subordination under the 1988 notification and takes effect from 30 September 2026, the date of publication in the Official Gazette.
Joint Commissioners of Income-tax (Appeals) and Additional Commissioners of Income-tax (Appeals) are placed under the control of the Principal Chief Commissioners of Income-tax or Chief Commissioners of Income-tax within whose jurisdiction they perform their functions. This substitutes the existing clause governing their subordination under the 1988 notification and takes effect from 30 September 2026, the date of publication in the Official Gazette.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908