Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
Juridical seat versus arbitral venue determines supervisory court jurisdiction, while timely award challenges remain within the prescribed limitation ...
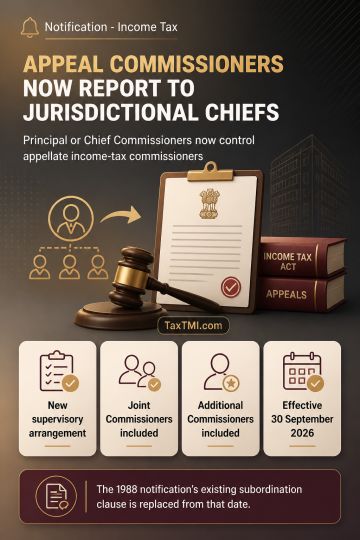
Joint Commissioners of Income-tax (Appeals) and Additional Commissioners of Income-tax (Appeals) are placed under the control of the Principal Chief Commissioners of Income-tax or Chief Commissioners of Income-tax within whose jurisdiction they perform their functions. This substitutes the existing clause governing their subordination under the 1988 notification and takes effect from 30 September 2026, the date of publication in the Official Gazette.
Joint Commissioners of Income-tax (Appeals) and Additional Commissioners of Income-tax (Appeals) are placed under the control of the Principal Chief Commissioners of Income-tax or Chief Commissioners of Income-tax within whose jurisdiction they perform their functions. This substitutes the existing clause governing their subordination under the 1988 notification and takes effect from 30 September 2026, the date of publication in the Official Gazette.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905