Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
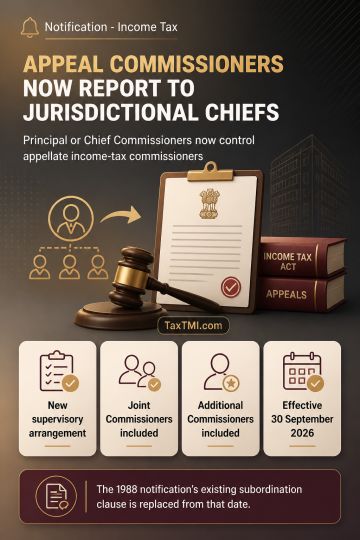
Joint Commissioners of Income-tax (Appeals) and Additional Commissioners of Income-tax (Appeals) are placed under the control of the Principal Chief Commissioners of Income-tax or Chief Commissioners of Income-tax within whose jurisdiction they perform their functions. This substitutes the existing clause governing their subordination under the 1988 notification and takes effect from 30 September 2026, the date of publication in the Official Gazette.
Joint Commissioners of Income-tax (Appeals) and Additional Commissioners of Income-tax (Appeals) are placed under the control of the Principal Chief Commissioners of Income-tax or Chief Commissioners of Income-tax within whose jurisdiction they perform their functions. This substitutes the existing clause governing their subordination under the 1988 notification and takes effect from 30 September 2026, the date of publication in the Official Gazette.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908