SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Page of 4908
Press 'Enter' after typing page number.
701 to 720 of 98141 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
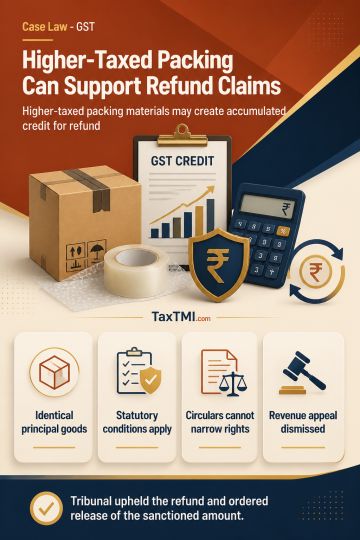
Refund of unutilised input tax credit under an inverted duty structure remains available where higher-taxed packing materials used to make sulphur marketable in customised packets cause credit accumulation, even though the principal goods at input and output stages are identical. Statutory refund conditions do not exclude such claims based on identity of the principal goods. CBIC circulars issued for uniform implementation cannot add restrictions or curtail the statutory entitlement. The Tribunal upheld the taxpayer's refund and directed release of the sanctioned amount, dismissing the Revenue's appeal.
Refund of unutilised input tax credit under an inverted duty structure remains available where higher-taxed packing materials used to make sulphur marketable in customised packets cause credit accumulation, even though the principal goods at input and output stages are identical. Statutory refund conditions do not exclude such claims based on identity of the principal goods. CBIC circulars issued for uniform implementation cannot add restrictions or curtail the statutory entitlement. The Tribunal upheld the taxpayer's refund and directed release of the sanctioned amount, dismissing the Revenue's appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908