Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
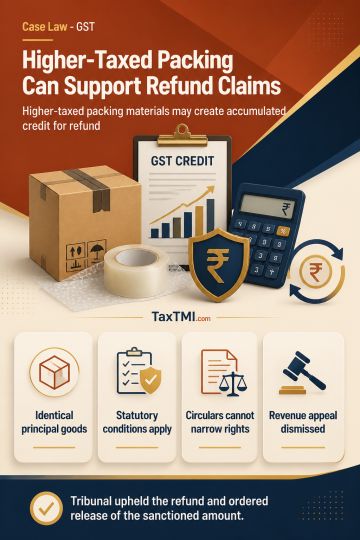
Refund of unutilised input tax credit under an inverted duty structure remains available where higher-taxed packing materials used to make sulphur marketable in customised packets cause credit accumulation, even though the principal goods at input and output stages are identical. Statutory refund conditions do not exclude such claims based on identity of the principal goods. CBIC circulars issued for uniform implementation cannot add restrictions or curtail the statutory entitlement. The Tribunal upheld the taxpayer's refund and directed release of the sanctioned amount, dismissing the Revenue's appeal.
Refund of unutilised input tax credit under an inverted duty structure remains available where higher-taxed packing materials used to make sulphur marketable in customised packets cause credit accumulation, even though the principal goods at input and output stages are identical. Statutory refund conditions do not exclude such claims based on identity of the principal goods. CBIC circulars issued for uniform implementation cannot add restrictions or curtail the statutory entitlement. The Tribunal upheld the taxpayer's refund and directed release of the sanctioned amount, dismissing the Revenue's appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910