Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
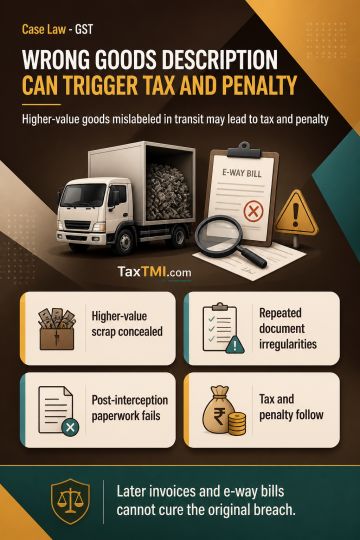
Transporting separately identifiable higher-value copper scrap under transit documents describing aluminium scrap constitutes more than a classification dispute or clerical error and supports an inference of intent to evade tax. Tax and penalty under section 129 may follow where the discrepancy conceals higher-value goods, particularly alongside repeated document irregularities. An invoice and e-way bill generated only after interception are post-detection measures; without statutory authority, they cannot validate the original transit-document breach or rebut the inference of tax evasion.
Transporting separately identifiable higher-value copper scrap under transit documents describing aluminium scrap constitutes more than a classification dispute or clerical error and supports an inference of intent to evade tax. Tax and penalty under section 129 may follow where the discrepancy conceals higher-value goods, particularly alongside repeated document irregularities. An invoice and e-way bill generated only after interception are post-detection measures; without statutory authority, they cannot validate the original transit-document breach or rebut the inference of tax evasion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915