Indirect corporate control can create related-party status, excluding financial creditors from Committee of Creditors representation, participation an...
Scientific research association approval requires continuing SIRO status, annual donation reporting, and donor certificates for the approved foundatio...
Scientific research institution approval is conditional on SIRO recognition, annual donation reporting, donor certification, and prescribed compliance...
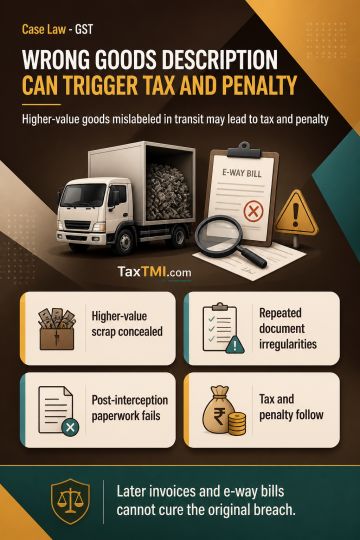
Transporting separately identifiable higher-value copper scrap under transit documents describing aluminium scrap constitutes more than a classification dispute or clerical error and supports an inference of intent to evade tax. Tax and penalty under section 129 may follow where the discrepancy conceals higher-value goods, particularly alongside repeated document irregularities. An invoice and e-way bill generated only after interception are post-detection measures; without statutory authority, they cannot validate the original transit-document breach or rebut the inference of tax evasion.
Transporting separately identifiable higher-value copper scrap under transit documents describing aluminium scrap constitutes more than a classification dispute or clerical error and supports an inference of intent to evade tax. Tax and penalty under section 129 may follow where the discrepancy conceals higher-value goods, particularly alongside repeated document irregularities. An invoice and e-way bill generated only after interception are post-detection measures; without statutory authority, they cannot validate the original transit-document breach or rebut the inference of tax evasion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908