Appellate jurisdiction over baggage imports is excluded, requiring confiscation challenges involving passenger-carried gold to proceed by statutory re...
Article 227 review permits intervention in arbitration only for manifest, patent inherent jurisdictional defects, not representational authority dispu...
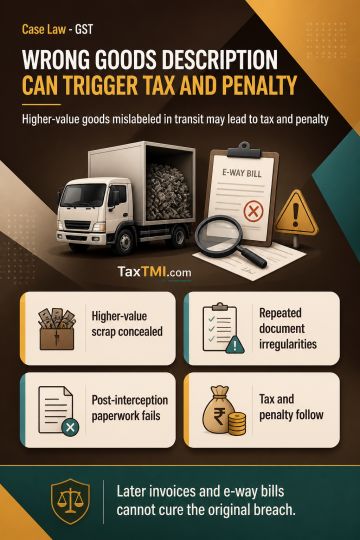
Transporting separately identifiable higher-value copper scrap under transit documents describing aluminium scrap constitutes more than a classification dispute or clerical error and supports an inference of intent to evade tax. Tax and penalty under section 129 may follow where the discrepancy conceals higher-value goods, particularly alongside repeated document irregularities. An invoice and e-way bill generated only after interception are post-detection measures; without statutory authority, they cannot validate the original transit-document breach or rebut the inference of tax evasion.
Transporting separately identifiable higher-value copper scrap under transit documents describing aluminium scrap constitutes more than a classification dispute or clerical error and supports an inference of intent to evade tax. Tax and penalty under section 129 may follow where the discrepancy conceals higher-value goods, particularly alongside repeated document irregularities. An invoice and e-way bill generated only after interception are post-detection measures; without statutory authority, they cannot validate the original transit-document breach or rebut the inference of tax evasion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910