Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
Page of 4915
Press 'Enter' after typing page number.
221 to 240 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
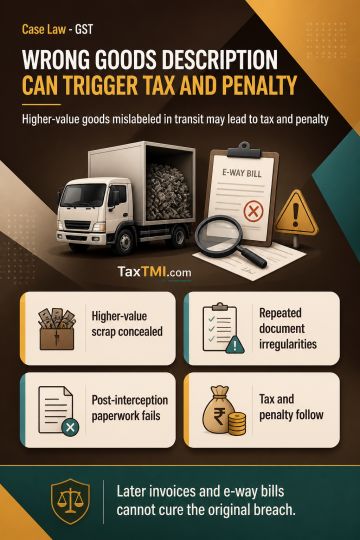
Transporting separately identifiable higher-value copper scrap under transit documents describing aluminium scrap constitutes more than a classification dispute or clerical error and supports an inference of intent to evade tax. Tax and penalty under section 129 may follow where the discrepancy conceals higher-value goods, particularly alongside repeated document irregularities. An invoice and e-way bill generated only after interception are post-detection measures; without statutory authority, they cannot validate the original transit-document breach or rebut the inference of tax evasion.
Transporting separately identifiable higher-value copper scrap under transit documents describing aluminium scrap constitutes more than a classification dispute or clerical error and supports an inference of intent to evade tax. Tax and penalty under section 129 may follow where the discrepancy conceals higher-value goods, particularly alongside repeated document irregularities. An invoice and e-way bill generated only after interception are post-detection measures; without statutory authority, they cannot validate the original transit-document breach or rebut the inference of tax evasion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915