Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
Factory-consumption condition restricts solar module parts exemption and excludes imported aluminium profiles fabricated outside the production factor...
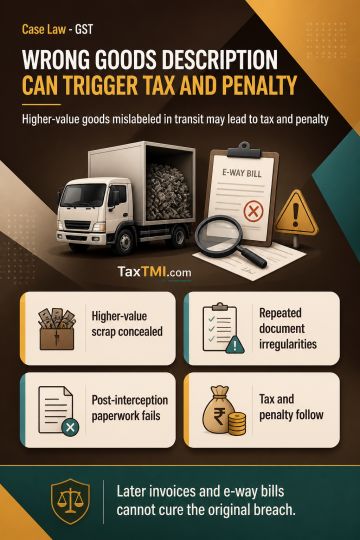
Transporting separately identifiable higher-value copper scrap under transit documents describing aluminium scrap constitutes more than a classification dispute or clerical error and supports an inference of intent to evade tax. Tax and penalty under section 129 may follow where the discrepancy conceals higher-value goods, particularly alongside repeated document irregularities. An invoice and e-way bill generated only after interception are post-detection measures; without statutory authority, they cannot validate the original transit-document breach or rebut the inference of tax evasion.
Transporting separately identifiable higher-value copper scrap under transit documents describing aluminium scrap constitutes more than a classification dispute or clerical error and supports an inference of intent to evade tax. Tax and penalty under section 129 may follow where the discrepancy conceals higher-value goods, particularly alongside repeated document irregularities. An invoice and e-way bill generated only after interception are post-detection measures; without statutory authority, they cannot validate the original transit-document breach or rebut the inference of tax evasion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913