Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
Juridical seat versus arbitral venue determines supervisory court jurisdiction, while timely award challenges remain within the prescribed limitation ...
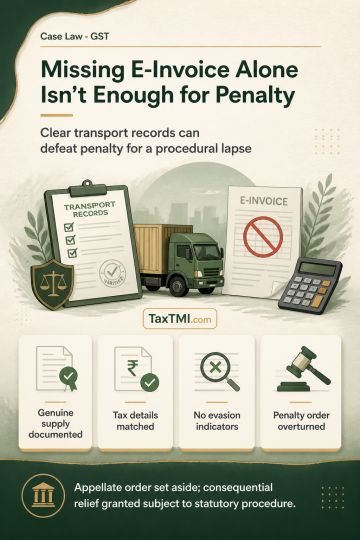
Non-generation of an e-invoice bearing IRN/QR Code before movement of goods is a procedural breach, but it does not by itself warrant detention penalty under Section 129. Where the tax invoice, e-way bill and lorry receipt identify the parties, goods, value and tax liability, and a later e-invoice matches the transaction, the lapse does not conclusively establish intent to evade tax absent fictitious documents, mismatched goods, value suppression or concealed supply. On these facts, the Section 129 penalty was unsustainable, the appellate order was set aside, and consequential relief was granted subject to statutory procedure.
Non-generation of an e-invoice bearing IRN/QR Code before movement of goods is a procedural breach, but it does not by itself warrant detention penalty under Section 129. Where the tax invoice, e-way bill and lorry receipt identify the parties, goods, value and tax liability, and a later e-invoice matches the transaction, the lapse does not conclusively establish intent to evade tax absent fictitious documents, mismatched goods, value suppression or concealed supply. On these facts, the Section 129 penalty was unsustainable, the appellate order was set aside, and consequential relief was granted subject to statutory procedure.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908