Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Page of 4915
Press 'Enter' after typing page number.
261 to 280 of 98291 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
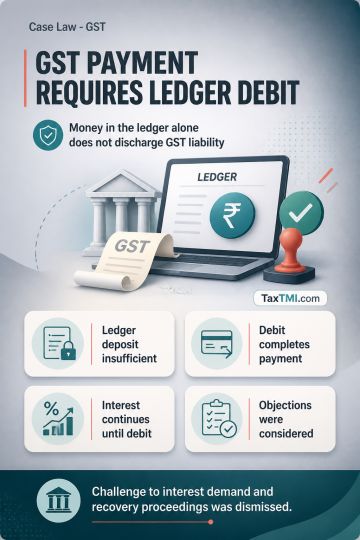
Self-assessed GST liability is discharged only when amounts credited to the Electronic Cash Ledger are debited and appropriated towards the relevant liability through the return. Mere deposit in the ledger before the return due date does not constitute payment or prevent interest under Section 50(1); interest accrues until actual debit, notwithstanding unsubstantiated technical difficulties. Recovery of the resulting interest after issuance of notice and consideration of objections does not breach principles of natural justice. The challenge to the interest demand and recovery proceedings was dismissed.
Self-assessed GST liability is discharged only when amounts credited to the Electronic Cash Ledger are debited and appropriated towards the relevant liability through the return. Mere deposit in the ledger before the return due date does not constitute payment or prevent interest under Section 50(1); interest accrues until actual debit, notwithstanding unsubstantiated technical difficulties. Recovery of the resulting interest after issuance of notice and consideration of objections does not breach principles of natural justice. The challenge to the interest demand and recovery proceedings was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915