Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
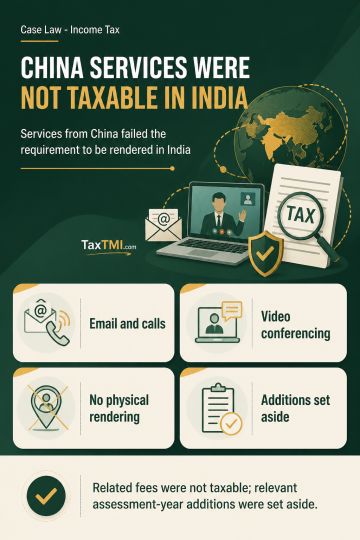
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
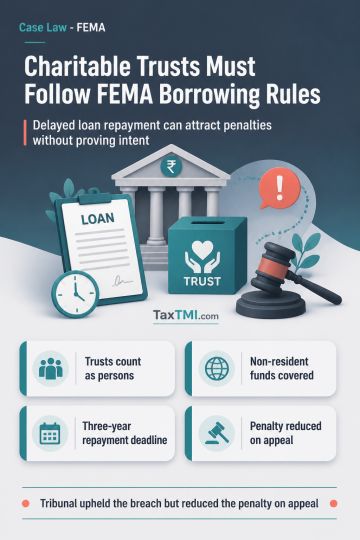
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
Input tax credit remains conditional on actual payment of the tax charged by the supplier to the Government. The statutory conditions for credit operate conjointly; a recipient who avails credit without ensuring that the supplier paid the corresponding tax cannot retain it, and the credit is recoverable according to law. Supplier insolvency and an approved insolvency resolution plan do not waive or displace this statutory tax-payment condition. The writ petition challenging recovery of the credit was dismissed.
Input tax credit remains conditional on actual payment of the tax charged by the supplier to the Government. The statutory conditions for credit operate conjointly; a recipient who avails credit without ensuring that the supplier paid the corresponding tax cannot retain it, and the credit is recoverable according to law. Supplier insolvency and an approved insolvency resolution plan do not waive or displace this statutory tax-payment condition. The writ petition challenging recovery of the credit was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915