Transfer-pricing aggregation of distinct support-service and subcontract transactions was rejected, while debt-free receivables attracted no notional ...
Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
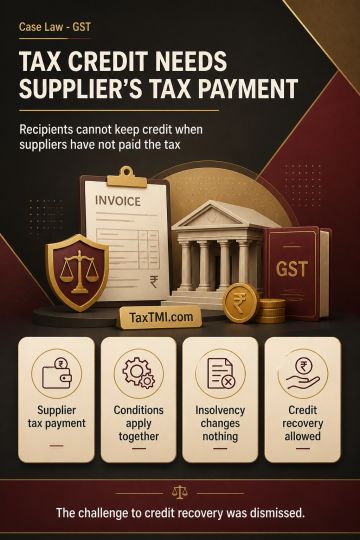
Input tax credit remains conditional on actual payment of the tax charged by the supplier to the Government. The statutory conditions for credit operate conjointly; a recipient who avails credit without ensuring that the supplier paid the corresponding tax cannot retain it, and the credit is recoverable according to law. Supplier insolvency and an approved insolvency resolution plan do not waive or displace this statutory tax-payment condition. The writ petition challenging recovery of the credit was dismissed.
Input tax credit remains conditional on actual payment of the tax charged by the supplier to the Government. The statutory conditions for credit operate conjointly; a recipient who avails credit without ensuring that the supplier paid the corresponding tax cannot retain it, and the credit is recoverable according to law. Supplier insolvency and an approved insolvency resolution plan do not waive or displace this statutory tax-payment condition. The writ petition challenging recovery of the credit was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908