Packing-material input credits support inverted-duty refunds for packaged tea, while rate-reduction and concessional-supply circulars remain inapplica...
Government road-restoration services for commercial pipeline work attract reverse-charge GST, while portal-issued proceedings remain valid without a p...
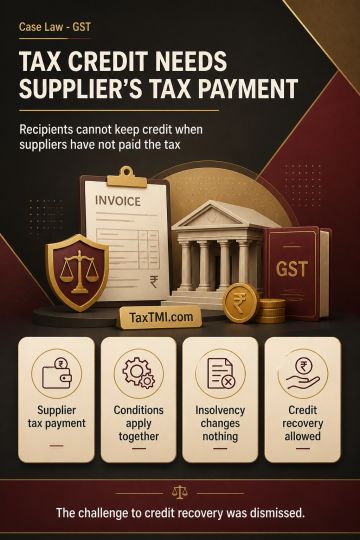
Input tax credit remains conditional on actual payment of the tax charged by the supplier to the Government. The statutory conditions for credit operate conjointly; a recipient who avails credit without ensuring that the supplier paid the corresponding tax cannot retain it, and the credit is recoverable according to law. Supplier insolvency and an approved insolvency resolution plan do not waive or displace this statutory tax-payment condition. The writ petition challenging recovery of the credit was dismissed.
Input tax credit remains conditional on actual payment of the tax charged by the supplier to the Government. The statutory conditions for credit operate conjointly; a recipient who avails credit without ensuring that the supplier paid the corresponding tax cannot retain it, and the credit is recoverable according to law. Supplier insolvency and an approved insolvency resolution plan do not waive or displace this statutory tax-payment condition. The writ petition challenging recovery of the credit was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916