Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Page of 4912
Press 'Enter' after typing page number.
521 to 540 of 98239 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
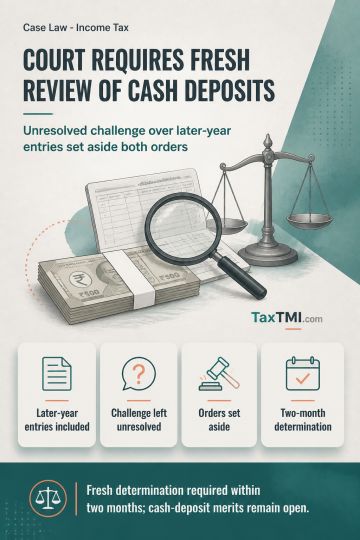
Cash and transfer entries from a subsequent financial year were included in the Assessment Year 2022-23 assessment, despite the relevant year being Financial Year 2021-22. The High Court treated the unresolved revisional challenge to those entries as material and held that its inadequate consideration vitiated both the assessment and revisional orders. Those orders were set aside, and the assessing authority must make a fresh determination within two months in accordance with law. The merits of the unexplained cash-deposit addition remain open.
Cash and transfer entries from a subsequent financial year were included in the Assessment Year 2022-23 assessment, despite the relevant year being Financial Year 2021-22. The High Court treated the unresolved revisional challenge to those entries as material and held that its inadequate consideration vitiated both the assessment and revisional orders. Those orders were set aside, and the assessing authority must make a fresh determination within two months in accordance with law. The merits of the unexplained cash-deposit addition remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912