Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
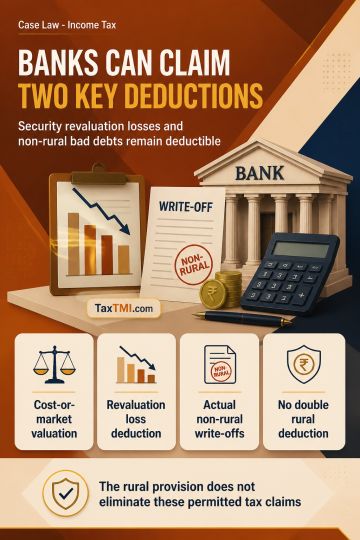
Government securities held to maturity by a bank are treated as stock-in-trade and may be valued at cost or market value, whichever is lower. Resulting revaluation loss is deductible. Bad debts actually written off in respect of non-rural advances remain deductible despite a provision for bad and doubtful debts relating to rural advances. The proviso to section 36(1)(vii) prevents double deduction for rural advances but does not restrict deductions for actual write-offs of non-rural debts.
Government securities held to maturity by a bank are treated as stock-in-trade and may be valued at cost or market value, whichever is lower. Resulting revaluation loss is deductible. Bad debts actually written off in respect of non-rural advances remain deductible despite a provision for bad and doubtful debts relating to rural advances. The proviso to section 36(1)(vii) prevents double deduction for rural advances but does not restrict deductions for actual write-offs of non-rural debts.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913