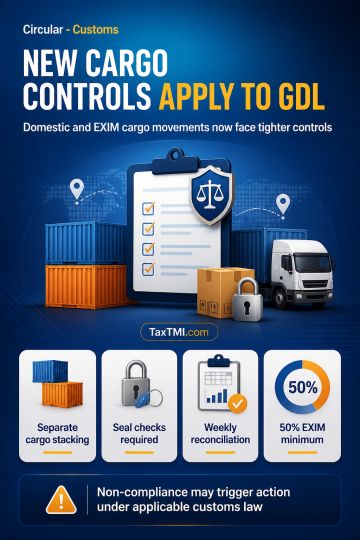
Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
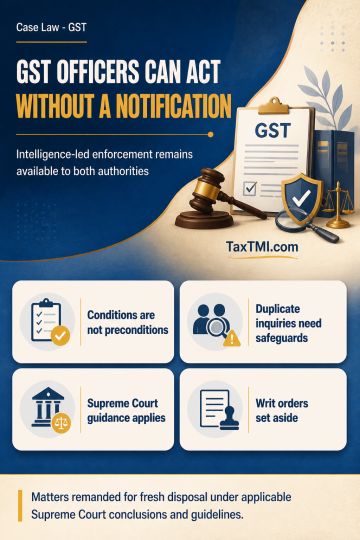
GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
Page of 4910
Press 'Enter' after typing page number.
641 to 660 of 98195 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Government securities held to maturity by a bank are treated as stock-in-trade and may be valued at cost or market value, whichever is lower. Resulting revaluation loss is deductible. Bad debts actually written off in respect of non-rural advances remain deductible despite a provision for bad and doubtful debts relating to rural advances. The proviso to section 36(1)(vii) prevents double deduction for rural advances but does not restrict deductions for actual write-offs of non-rural debts.
Government securities held to maturity by a bank are treated as stock-in-trade and may be valued at cost or market value, whichever is lower. Resulting revaluation loss is deductible. Bad debts actually written off in respect of non-rural advances remain deductible despite a provision for bad and doubtful debts relating to rural advances. The proviso to section 36(1)(vii) prevents double deduction for rural advances but does not restrict deductions for actual write-offs of non-rural debts.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910