Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Page of 4921
Press 'Enter' after typing page number.
281 to 300 of 98411 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
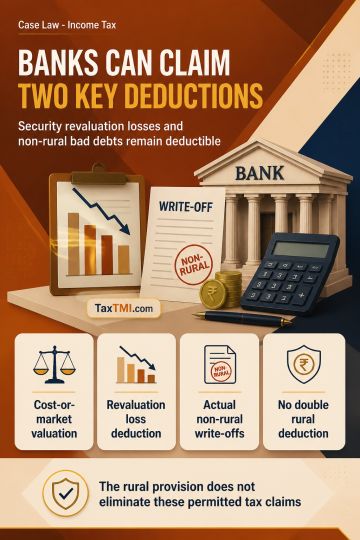
Government securities held to maturity by a bank are treated as stock-in-trade and may be valued at cost or market value, whichever is lower. Resulting revaluation loss is deductible. Bad debts actually written off in respect of non-rural advances remain deductible despite a provision for bad and doubtful debts relating to rural advances. The proviso to section 36(1)(vii) prevents double deduction for rural advances but does not restrict deductions for actual write-offs of non-rural debts.
Government securities held to maturity by a bank are treated as stock-in-trade and may be valued at cost or market value, whichever is lower. Resulting revaluation loss is deductible. Bad debts actually written off in respect of non-rural advances remain deductible despite a provision for bad and doubtful debts relating to rural advances. The proviso to section 36(1)(vii) prevents double deduction for rural advances but does not restrict deductions for actual write-offs of non-rural debts.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921