Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
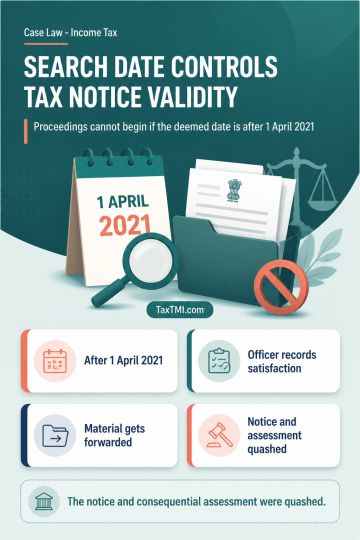
Section 153C proceedings cannot be initiated where the deemed date of search falls after 1 April 2021. Under the proviso to section 153C(1), that date is when the searched person's Assessing Officer records satisfaction and forwards seized material to the assessee's Assessing Officer. Where forwarding occurred after that date, section 153C(3) rendered the provision inapplicable, resulting in quashing of the notice and consequential assessment; other grounds became academic.
Section 153C proceedings cannot be initiated where the deemed date of search falls after 1 April 2021. Under the proviso to section 153C(1), that date is when the searched person's Assessing Officer records satisfaction and forwards seized material to the assessee's Assessing Officer. Where forwarding occurred after that date, section 153C(3) rendered the provision inapplicable, resulting in quashing of the notice and consequential assessment; other grounds became academic.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910