Indirect corporate control can create related-party status, excluding financial creditors from Committee of Creditors representation, participation an...
Scientific research association approval requires continuing SIRO status, annual donation reporting, and donor certificates for the approved foundatio...
Scientific research institution approval is conditional on SIRO recognition, annual donation reporting, donor certification, and prescribed compliance...
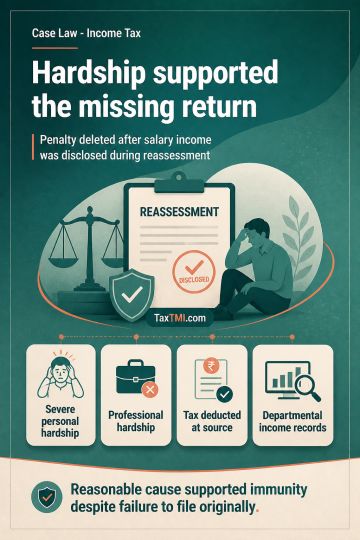
Section 270A penalty for misreporting income was deleted where failure to file the original return was unintentional and resulted from severe personal and professional hardship. Salary income had already been subjected to tax deduction at source and was available in departmental records. The assessee disclosed that income in response to reassessment proceedings, and the reassessment accepted the returned income. These facts established reasonable cause and supported immunity from penalty despite non-filing of the original return.
Section 270A penalty for misreporting income was deleted where failure to file the original return was unintentional and resulted from severe personal and professional hardship. Salary income had already been subjected to tax deduction at source and was available in departmental records. The assessee disclosed that income in response to reassessment proceedings, and the reassessment accepted the returned income. These facts established reasonable cause and supported immunity from penalty despite non-filing of the original return.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912