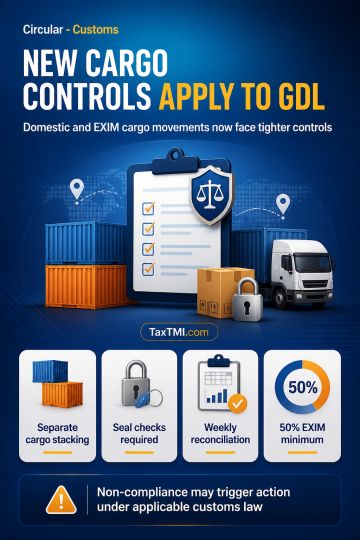
Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
Page of 4910
Press 'Enter' after typing page number.
641 to 660 of 98195 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Section 270A penalty for misreporting income was deleted where failure to file the original return was unintentional and resulted from severe personal and professional hardship. Salary income had already been subjected to tax deduction at source and was available in departmental records. The assessee disclosed that income in response to reassessment proceedings, and the reassessment accepted the returned income. These facts established reasonable cause and supported immunity from penalty despite non-filing of the original return.
Section 270A penalty for misreporting income was deleted where failure to file the original return was unintentional and resulted from severe personal and professional hardship. Salary income had already been subjected to tax deduction at source and was available in departmental records. The assessee disclosed that income in response to reassessment proceedings, and the reassessment accepted the returned income. These facts established reasonable cause and supported immunity from penalty despite non-filing of the original return.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910