SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
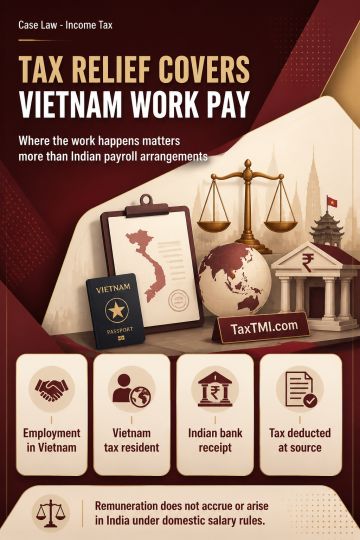
Salary earned by a Vietnam tax resident for employment exercised and services rendered in Vietnam qualifies for exemption in India under Article 16(1) of the India-Vietnam DTAA, read with section 90. Taxability depends on where employment is exercised and services are performed, rather than on the continued use of an Indian payroll, payment into an Indian bank account, or tax deducted at source. On that basis, remuneration for Vietnam-based employment does not accrue or arise in India under the domestic salary-tax provisions, and the claimed treaty exemption applies.
Salary earned by a Vietnam tax resident for employment exercised and services rendered in Vietnam qualifies for exemption in India under Article 16(1) of the India-Vietnam DTAA, read with section 90. Taxability depends on where employment is exercised and services are performed, rather than on the continued use of an Indian payroll, payment into an Indian bank account, or tax deducted at source. On that basis, remuneration for Vietnam-based employment does not accrue or arise in India under the domestic salary-tax provisions, and the claimed treaty exemption applies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916