Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
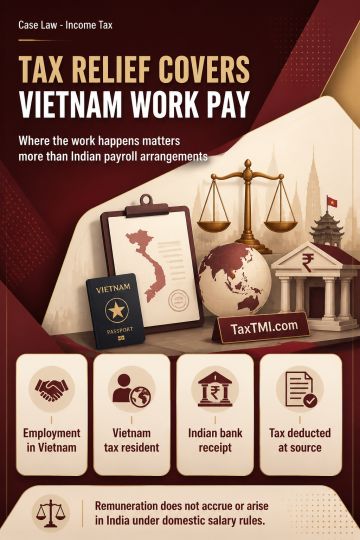
Salary earned by a Vietnam tax resident for employment exercised and services rendered in Vietnam qualifies for exemption in India under Article 16(1) of the India-Vietnam DTAA, read with section 90. Taxability depends on where employment is exercised and services are performed, rather than on the continued use of an Indian payroll, payment into an Indian bank account, or tax deducted at source. On that basis, remuneration for Vietnam-based employment does not accrue or arise in India under the domestic salary-tax provisions, and the claimed treaty exemption applies.
Salary earned by a Vietnam tax resident for employment exercised and services rendered in Vietnam qualifies for exemption in India under Article 16(1) of the India-Vietnam DTAA, read with section 90. Taxability depends on where employment is exercised and services are performed, rather than on the continued use of an Indian payroll, payment into an Indian bank account, or tax deducted at source. On that basis, remuneration for Vietnam-based employment does not accrue or arise in India under the domestic salary-tax provisions, and the claimed treaty exemption applies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4907