Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
Page of 4915
Press 'Enter' after typing page number.
221 to 240 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Schizophrenia Research Foundation (I), Chennai is approved as an...
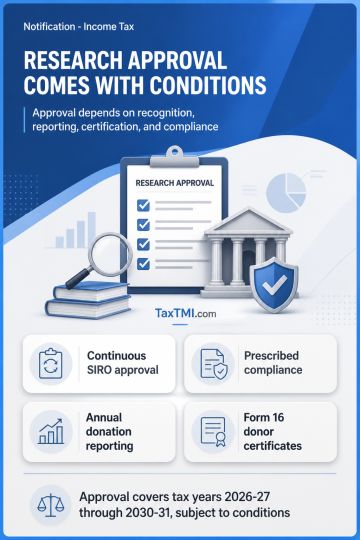
Scientific research institution approval is conditional on SIRO recognition, annual donation reporting, donor certification, and prescribed compliance.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Schizophrenia Research Foundation (I), Chennai is approved as an "other institution" for scientific research under the Income-tax Act, 2025, for tax years 2026-27 through 2030-31. The approval remains conditional on continuous SIRO approval for each effective tax year, compliance with prescribed requirements, annual preparation and delivery of the donation statement in Form 15 by 31 May following the relevant tax year, and issuance of Form 16 donation certificates to donors. These conditions govern the institution's continued eligibility under the approval.
Schizophrenia Research Foundation (I), Chennai is approved as an "other institution" for scientific research under the Income-tax Act, 2025, for tax years 2026-27 through 2030-31. The approval remains conditional on continuous SIRO approval for each effective tax year, compliance with prescribed requirements, annual preparation and delivery of the donation statement in Form 15 by 31 May following the relevant tax year, and issuance of Form 16 donation certificates to donors. These conditions govern the institution's continued eligibility under the approval.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915