Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Page of 4915
Press 'Enter' after typing page number.
341 to 360 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
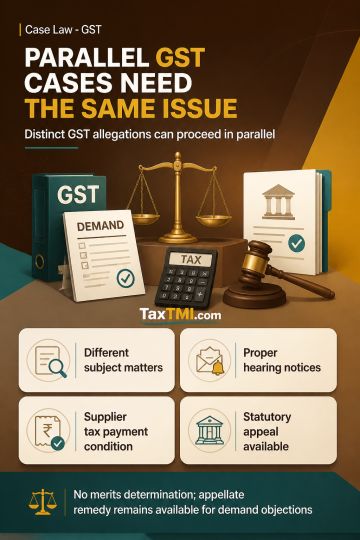
Parallel GST proceedings are barred only where proceedings under the State enactment were initiated earlier and both proceedings concern the same subject matter. Turnover reconciliation based on GSTR-3B and allegations of issuing invoices without supply and wrongly passing input tax credit involve distinct subject matters, so the bar does not apply. Ex parte adjudication does not breach natural justice where hearing notices are properly sent and the noticee neither appears nor provides a substantive reply. Input tax credit may validly be conditional on the supplier's payment of tax, a position affirmed by the Supreme Court. Statutory appellate remedy remains available for objections to the demand without a merits determination.
Parallel GST proceedings are barred only where proceedings under the State enactment were initiated earlier and both proceedings concern the same subject matter. Turnover reconciliation based on GSTR-3B and allegations of issuing invoices without supply and wrongly passing input tax credit involve distinct subject matters, so the bar does not apply. Ex parte adjudication does not breach natural justice where hearing notices are properly sent and the noticee neither appears nor provides a substantive reply. Input tax credit may validly be conditional on the supplier's payment of tax, a position affirmed by the Supreme Court. Statutory appellate remedy remains available for objections to the demand without a merits determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915