Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensa...
Resolution plan finality extinguishes unquantified operational-creditor claims and pending proceedings unless the approved plan expressly preserves th...
Stakeholder-list modification permits liquidators to update entries on new information, subject to notifying the Adjudicating Authority within prescri...
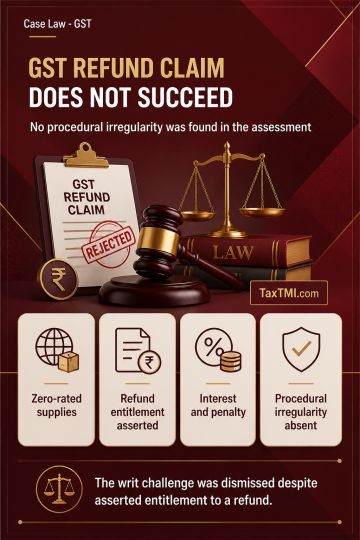
GST assessment order was challenged on the basis that zero-rated supplies entitled the petitioner to a refund under the IGST and CGST/TNGST provisions. The assessment also required payment of interest and penalty under the respective GST enactments. No procedural irregularity was found in the assessment process, and the writ challenge was dismissed. The dispute therefore centred on the procedural validity of the assessment despite the asserted entitlement to a refund for zero-rated supplies.
GST assessment order was challenged on the basis that zero-rated supplies entitled the petitioner to a refund under the IGST and CGST/TNGST provisions. The assessment also required payment of interest and penalty under the respective GST enactments. No procedural irregularity was found in the assessment process, and the writ challenge was dismissed. The dispute therefore centred on the procedural validity of the assessment despite the asserted entitlement to a refund for zero-rated supplies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918